
Key Takeaways
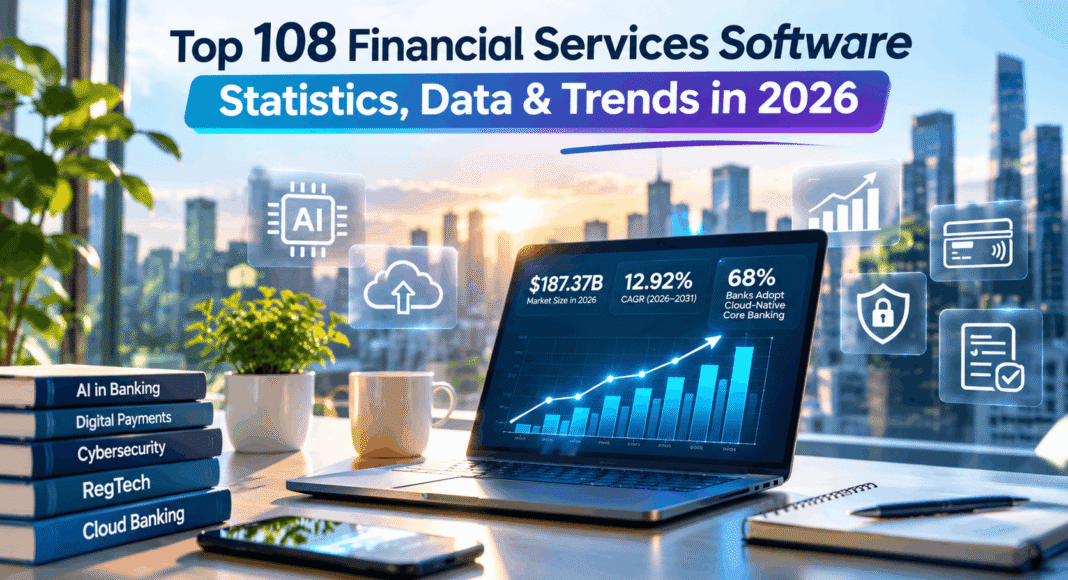
- Financial Services Software Market Growth: The global financial services applications market is projected to reach $187.37 billion in 2026 and grow to $343.64 billion by 2031, driven by digital transformation, cloud banking, and financial automation.
- AI Adoption and Cloud Banking Transformation: Approximately 81% of financial services firms are adopting AI, while 68% of banks have reportedly implemented cloud-native core banking platforms, accelerating innovation in fraud detection, risk management, and operational efficiency.
- Digital Payments, Cybersecurity, and RegTech Trends: Global digital payment transaction values are forecast to reach $37.45 trillion in 2026, highlighting growing demand for secure financial software, AI-powered cybersecurity, regulatory compliance solutions, and real-time payment technologies.
Financial services software is transforming banking, payments, insurance, and financial operations in 2026. The global financial services applications market is projected to reach $187.37 billion in 2026 and $343.64 billion by 2031. Explore 108 key statistics covering AI adoption, cloud banking, cybersecurity, digital payments, regulatory compliance, and emerging financial technology trends.
The financial services software industry is undergoing a major transformation in 2026, driven by artificial intelligence, cloud computing, digital banking, cybersecurity, and evolving regulatory requirements. As banks, insurance companies, fintech startups, and financial institutions accelerate digital transformation, demand for advanced financial services software continues to grow. From AI-powered fraud detection and automated compliance management to real-time payments and cloud-based core banking systems, financial technology is fundamentally reshaping how organizations manage operations, serve customers, and mitigate financial risks.
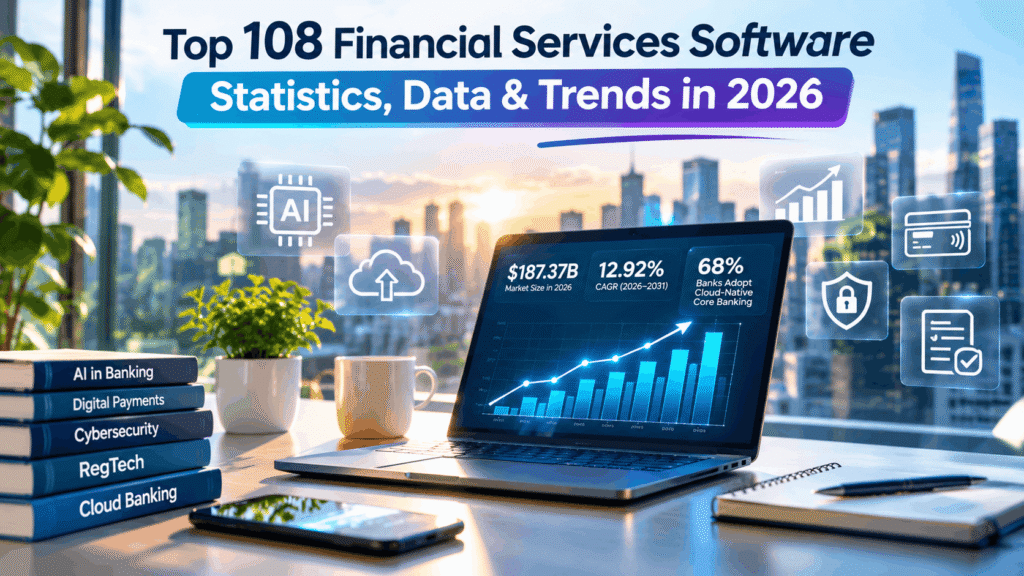
According to industry projections, the global financial services applications market is expected to reach $187.37 billion in 2026, expanding at a compound annual growth rate (CAGR) of 12.92% to approximately $343.64 billion by 2031. Meanwhile, artificial intelligence is becoming increasingly central to financial operations, with 81% of surveyed financial services firms adopting AI at some level and 52% piloting or advancing agentic AI implementations. Cloud adoption is also accelerating, with approximately 68% of banks reportedly adopting cloud-native platforms for core banking operations, reflecting the industry’s shift toward scalable, flexible, and cost-efficient technology infrastructure.
The rapid expansion of digital financial services is creating significant opportunities alongside new operational challenges. Global digital payment transaction values are projected to reach $37.45 trillion in 2026, while mobile banking adoption continues to increase across major markets. However, cybersecurity threats, financial fraud, regulatory compliance pressures, and legacy system modernization remain critical concerns. With the average financial services data breach costing approximately $5.56 million in 2025, financial institutions are prioritizing investments in cybersecurity software, AI-driven risk management, and regulatory technology (RegTech) to strengthen operational resilience.
Emerging financial services software trends in 2026 also highlight the growing importance of open banking, embedded finance, insurance technology, and intelligent automation. Financial institutions are increasingly integrating machine learning, predictive analytics, API-driven platforms, and generative AI into their technology ecosystems to improve decision-making, streamline workflows, reduce operational costs, and deliver more personalized customer experiences. At the same time, regulatory developments and rising customer expectations are encouraging software providers to deliver more secure, transparent, and interoperable solutions.
Understanding these developments is essential for financial institutions, fintech companies, software vendors, investors, and business leaders seeking to remain competitive in an increasingly digital financial landscape. This comprehensive guide to the Top 108 Financial Services Software Statistics, Data & Trends in 2026 explores the latest market size estimates, industry growth forecasts, AI adoption rates, cloud banking developments, cybersecurity statistics, digital payment trends, mobile banking usage, RegTech investments, and financial software purchasing behavior.
By examining 108 financial services software statistics and industry insights, this article provides a data-driven overview of the technologies, market forces, and emerging opportunities shaping the global financial services software market in 2026 and beyond. Whether evaluating financial technology investments, developing digital transformation strategies, researching fintech market opportunities, or comparing enterprise financial software solutions, these statistics offer valuable insights into the future of financial services technology.
Before we venture further into this article, we would like to share who we are and what we do.
About 9cv9
9cv9 is a business tech startup based in Singapore and Asia, with a strong presence all over the world.
With over ten years of startup and business experience, and being highly involved in connecting with thousands of companies and startups, the 9cv9 team has listed some of the top and best companies/tools in this review.
If you like to get your company listed in our top B2B software reviews, check out our world-class 9cv9 Media and PR service and pricing plans here.
Top 108 Financial Services Software Statistics, Data & Trends in 2026
🏦 Market Size & Growth
- The financial services applications market is valued at $187.37 billion in 2026, growing at a 12.92% CAGR to reach $343.64 billion by 2031. This trajectory signals that financial institutions are accelerating technology budgets faster than the broader enterprise software average, driven by regulatory deadlines and AI-enabled customer experience tools.
- A separate forecast pegs the global financial services software market at $180.96 billion in 2026, rising to $276.28 billion by 2030 at an 11.2% CAGR. The consistency across independent estimates reinforces that financial services software is now solidly a $150–190 billion global category entering 2026.
- The financial services software market is alternatively estimated at $144.64 billion in 2024, projected to reach $298.33 billion by 2033 at an 8.38% CAGR. Even the more conservative projections confirm a doubling of market value within roughly a decade.
- The U.S. financial services software market alone is projected at $45.88 billion in 2025. North America continues to anchor global software spending in this vertical thanks to mature banking infrastructure and heavy compliance obligations.
- China’s financial services software market is projected at $45.78 billion in 2025, nearly matching the U.S. This underscores how quickly Asia-Pacific has closed the technology-investment gap with Western markets.
- Europe’s financial services software market is projected at $33.77 billion in 2025. Europe’s growth is shaped heavily by regulatory mandates such as DORA and PSD2/PSD3, which compel continuous platform investment.
- The application software market as a whole (including financial services) could reach $780 billion by 2030, a 13% CAGR, driven partly by agentic AI. Financial services software is riding the same AI-driven expansion wave reshaping enterprise software broadly.
- Gartner predicts 40% of enterprise applications will integrate task-specific AI agents by the end of 2026, up from under 5% in 2025. This eightfold jump illustrates how quickly agentic AI is being embedded directly into financial software products.
- Digital transactions in financial services grew 32.6% in a recent measurement period. This growth rate highlights the sustained migration away from manual, paper-based financial processes.
- 39.2% of banks upgraded legacy platforms in 2023 for improved service delivery. Legacy modernization remains an active, ongoing priority rather than a one-time initiative for a large share of the banking sector.
- Cloud-based financial services software models represented 61.8% of enterprise usage versus 38.2% for on-premise deployments. Cloud has decisively overtaken on-premise as the default deployment choice for financial institutions.
- API adoption improved by 26.3% among regional banks in one recent measurement period. Rising API adoption reflects how deeply interconnected modern financial software stacks have become.
- 28.4% of fintech firms reported experiencing a security breach, while 21.7% delayed modernization due to migration and compliance risk. This tension between security concerns and the need to modernize is a defining constraint on the sector’s technology roadmap.
☁️ Core Banking & Cloud Infrastructure
- The core banking software market is projected to hit $27.6 billion in 2026, growing at a striking 48.50% CAGR toward $967.9 billion by 2035. Even accounting for forecasting variance across providers, the direction is unmistakable: core banking replacement cycles are accelerating sharply.
- A more conservative core banking estimate places the market at $10.41 billion in 2026, rising modestly to $12.88 billion by 2035. The wide spread between forecasts reflects differing definitions of “core banking software” scope, but all agree cloud and AI are reshaping the category.
- SaaS/hosted deployment is expected to hold 67.54% share of the core banking software market in 2026. Hosted and subscription-based core banking has become the clear preference over traditional licensed installations.
- About 68% of banks globally have adopted cloud-native platforms for core banking operations as of early 2026. More than two-thirds of the global banking industry has now moved past the cloud-hesitancy phase.
- Around 78% of banks have deployed SaaS-based core banking platforms, resulting in up to a 30% reduction in operational costs. The cost-efficiency case for SaaS core banking is now empirically demonstrated at scale.
- Nearly 89% of digital-only banks and neobanks launch with fully cloud-based core infrastructure. Cloud-native architecture has become the default starting point, not an eventual migration goal, for new banking entrants.
- Around 60% of banks migrated at least 30% of critical workloads to the cloud by 2026. Partial cloud migration has become mainstream even among institutions that have not fully abandoned on-premise systems.
- Legacy infrastructure maintenance continues to consume about 70% of bank technology budgets. This statistic explains why “rip and replace” core modernization remains financially difficult despite clear cloud benefits.
- North America’s core banking software market is projected to reach $9.6 billion in 2026. North America retains its lead position in absolute core banking software spend.
- Europe’s core banking software segment is projected to reach $5.24 billion in 2026, representing 22.80% of the global market. Regulatory pressure in the EU continues to be a significant driver of core banking upgrades.
- 60% of banks in North America, 82% in Europe, and 83% in Asia-Pacific are increasing cloud investments in the coming years. The universally high figures across all three major regions confirm cloud investment is now a near-consensus banking strategy.
- By 2030, Gartner projects 90% of all banking workloads will be cloud-based. This forecast effectively marks the end of the on-premise-first banking software era within this decade.
- 92% of bank executives report improved regulatory compliance after cloud adoption, and 94% report improved security. These figures directly counter the historical assumption that cloud deployments compromise regulatory or security posture.
- Approximately 71% of banking institutions implemented real-time payment processing integrated with centralized banking architecture in 2025. Real-time processing capability has become a baseline expectation rather than a differentiator.
- More than 58% of banking institutions implemented AI-assisted fraud monitoring within their core banking architecture. AI-driven fraud monitoring is increasingly built directly into core systems rather than bolted on separately.
- 68% of financial institutions adopted API-enabled banking frameworks to improve interoperability. API-first architecture has become the connective tissue linking payments, compliance, and customer engagement systems.
- Mobile banking interactions exceeded 240 billion annual sessions globally. This session volume illustrates the sheer scale of transaction infrastructure that core banking software must now reliably support.
- JPMorgan Chase increased technology investment to nearly $18 billion in 2025, deploying more than 175 AI use cases across banking operations. This single institution’s spend illustrates how large-scale financial technology investment has become at the enterprise tier.
- The cloud core banking platform market alone reached $1.6 billion in 2025, projected to grow to $11.1 billion by 2035 at a 21.4% CAGR. Even as a narrower sub-segment, cloud-native core banking is growing faster than the broader core banking category.
🤖 Artificial Intelligence in Financial Services
- 81% of surveyed financial services firms are adopting AI at some level as of early 2026, with 40% reaching advanced (“Scaling” or “Transforming”) maturity. AI adoption within financial services has moved decisively beyond the pilot stage for a large share of the industry.
- Fintechs lead incumbents in advanced AI adoption by 47% to 30%. Newer, less legacy-constrained fintech firms continue to outpace traditional institutions in translating AI investment into operational maturity.
- Only 14% of industry respondents currently see AI as transformational to their organizational strategy, despite 81% adoption. This gap between adoption breadth and strategic impact suggests many AI deployments remain tactical rather than transformational.
- 52% of financial institutions were piloting or had reached more advanced agentic AI deployment stages as of early 2026. Agentic AI adoption is trailing broader AI adoption but is still already a majority-engaged trend among financial firms.
- 44% of finance teams are expected to use agentic AI in 2026, representing an increase of over 600% year-over-year. This is one of the steepest year-over-year technology adoption curves recorded in the financial software space.
- Agentic AI could contribute $3 trillion in corporate productivity gains and a 5.4% average EBITDA improvement annually, based on research spanning 17 million companies. These figures illustrate the scale of the economic case driving continued agentic AI investment.
- Organizations achieve an average 2.3x return on agentic AI investments within 13 months. A sub-14-month payback period helps explain why boards are approving agentic AI budgets despite governance uncertainty.
- AI could reduce certain banking cost categories by as much as 70%, though the net effect nets out closer to 15–20% ($700–800 billion) after rising AI technology costs. This nuance is an important corrective to overly optimistic AI cost-savings headlines.
- Frontier firms leading in AI adoption achieve 2.84x returns on investment compared to just 0.84x for laggards. The gap between AI leaders and laggards is widening rather than narrowing, raising the competitive stakes of inaction.
- 78% of banks use AI-powered chatbots, and 67% apply AI specifically for fraud detection. Customer-facing AI and fraud-focused AI remain the two most mature use cases across the banking sector.
- 63% of financial institutions use AI for anti-money-laundering (AML) activities. AI-driven AML has moved from experimental status to a mainstream compliance tool for the majority of surveyed institutions.
- 90% of financial institutions use AI for fraud detection and investigation, and 64% specifically deploy AI agents for fraud-related tasks. Fraud detection remains the single most universally adopted AI use case in financial services.
- 75% of banks use AI agents in customer service, with AI chatbots increasing productivity by 70% while reducing costs by 50%. These productivity and cost figures make AI-driven customer service one of the clearest ROI cases in the sector.
- 61% of banks apply AI in loan processing, and 88% of companies use AI in at least one banking function. AI has effectively become ubiquitous across at least some part of the average bank’s operations.
- The EU AI Act’s full compliance requirements for high-risk AI systems—including credit scoring, AML profiling, and biometric verification—become enforceable from August 2, 2026. This regulatory deadline is set to significantly reshape AI vendor selection criteria across the European financial sector this year.
- Only 50% of the industry has adopted explainable AI methods, despite 78% of regulators rating explainability as critical or important. This gap between regulatory expectation and industry practice represents a material compliance risk heading into stricter 2026 enforcement.
- About two-thirds of industry respondents are not currently monitoring for bias or systemic discrimination in their AI systems. This finding highlights a significant governance blind spot even as AI adoption accelerates.
- The global AI-in-banking market stood at an estimated $15.2 billion in 2022, projected to grow to $64.03 billion by 2030 at a 19.7% CAGR. This standalone AI-in-banking figure illustrates how AI itself has become a distinct, fast-growing software sub-market.
- AI spending in financial services is forecast to reach $97 billion by 2027, growing at a 28.2% CAGR. This spending trajectory places AI among the fastest-growing line items in financial technology budgets.
- The generative AI subset within finance is projected to grow from $1.3 billion in 2023 to $14.9 billion by 2030. Generative AI’s roughly 11x growth over seven years reflects how quickly large language models have been operationalized in finance.
🔐 Cybersecurity, Fraud & Risk
- The average cost of a data breach in financial services reached $5.56 million in 2025, second only to healthcare. This figure underscores why cybersecurity remains one of the largest line items in financial services technology budgets.
- Banks and payment platforms absorb 34% of all observed Layer 3/4 DDoS attacks, the highest share of any industry tracked. Financial services firms face a disproportionate share of infrastructure-level cyberattacks relative to their share of the broader economy.
- Two-thirds of financial services organizations were hit by ransomware in the latest measured period. Ransomware has become less an “if” and more a “when” scenario for the majority of financial institutions.
- Third-party involvement in breaches has doubled to 30% across industries, a particularly sharp signal for finance given heavy reliance on vendor ecosystems. This trend elevates vendor risk management to a top-tier cybersecurity priority for financial software buyers.
- Exploitation of vulnerabilities, often in vendor-managed infrastructure, is now the initial access vector in 20% of breaches, up 34% year-over-year. This statistic reinforces that supply-chain security has become as critical as perimeter security.
- Extreme cyber losses in the financial sector have quadrupled since 2017, reaching $2.5 billion at the tail end of loss distributions. The growing “fat tail” of catastrophic cyber events is reshaping how institutions model systemic financial risk.
- Financial crime crossed $579.4 billion in global losses in 2025, with 67% of banks and fintechs reporting rising fraud rates. This figure demonstrates that despite heavy technology investment, fraud losses continue climbing in absolute terms.
- One in five financial institutions absorbed fraud losses exceeding $5 million in a single year. This concentration of large losses shows that fraud risk is unevenly but significantly distributed across the industry.
- The FBI’s IC3 recorded $16.6 billion in total internet crime losses in 2024, up from $12.5 billion the prior year — a roughly 33% increase. This year-over-year jump illustrates how rapidly online financial fraud is scaling relative to defensive investment.
- Business Email Compromise (BEC) alone accounted for $2.77 billion in losses across 21,442 complaints in 2024. BEC remains one of the most financially damaging and persistent categories of financial cybercrime.
- AI detects 30–50% more fraudulent transactions than traditional rule-based methods. This performance gap is a primary justification for the accelerating shift toward AI-native fraud detection platforms.
- AI reduced false positives in fraud detection by 60% for at least one major card network in a recent measurement period. Reducing false positives directly improves both customer experience and fraud team efficiency.
- 42% of card issuers and 26% of acquirers save over $5 million within two years using AI for payment fraud prevention. These savings figures provide a concrete ROI benchmark for AI-powered fraud tooling investment decisions.
- More than three in five financial organizations now use advanced machine learning for real-time fraud detection and automation. Machine learning has moved from a competitive advantage to table stakes for real-time fraud operations.
- Global information security spending is estimated at $183.9 billion, with continued growth toward over $300 billion by 2030. This spending trajectory confirms cybersecurity remains one of the fastest-compounding categories within financial technology budgets.
- AI-powered cybersecurity spending specifically within banking, financial services, and insurance is projected to grow from around $35.40 billion to $167.77 billion by 2035, an 18.9% CAGR. This sub-segment’s growth rate illustrates how AI and cybersecurity investment have become intertwined rather than separate budget lines.
- Half of all stolen check images appear on dark web platforms within eight days of theft, with 1.9 million stolen U.S. bank checks tracked across 700+ Telegram channels in a single year. This statistic highlights how traditional payment instruments like checks remain a persistent, digitally-industrialized fraud vector.
💳 Digital Payments & Open Banking
- The global digital payments market is projected to reach $37.45 trillion in total transaction value in 2026. This figure reflects the sheer scale of value now flowing through digital rather than cash-based payment rails worldwide.
- Mobile POS payments alone are projected to reach $28.32 trillion in transaction value in 2026. Mobile point-of-sale has become the single largest component within the broader digital payments category.
- The United States accounts for the highest cumulated digital payment transaction value globally, at $10.86 trillion in 2026. Despite global digitization, the U.S. remains the single largest national digital payments market by value.
- Open banking transactions are on track to exceed $116 billion globally by the end of 2026. This figure signals that open banking has moved well beyond experimentation into meaningful transactional scale.
- Real-time payments volume is expected to process $195 trillion globally by 2030, growing at a 21% CAGR. Real-time payment rails are becoming the fastest-growing segment of the global payments infrastructure.
- The global open banking market is projected to reach $43.22 billion in 2026, growing at a 21.00% CAGR toward $240.31 billion by 2035. Open banking’s growth rate outpaces most other financial software sub-segments over the coming decade.
- Europe holds approximately 36% of the global open banking market, the largest regional share. Europe’s regulatory head start under PSD2 continues to translate into commercial market leadership.
- Value-added services such as data enrichment, payment initiation, and identity verification now account for 54% of total open banking market revenue in 2026. The monetization center of gravity has shifted from basic connectivity fees toward higher-value services.
- Over 75 million consents are active in Brazil’s open finance ecosystem as of January 2026. Brazil’s open finance framework, integrated tightly with its instant payments system, stands as a global benchmark for adoption scale.
- In the UK, open banking usage grew 34% year-on-year as of July 2025, reaching 15.16 million active users by that point. The UK continues to demonstrate some of the most mature open banking adoption metrics of any single market.
- 33.1 million UK users are expected by 2026, covering 60.5% of the UK adult population. This figure indicates open banking is approaching mainstream, majority-adoption status in one of its most advanced markets.
- Global BNPL (Buy Now, Pay Later) market size is projected at $618 billion in 2026, up from $560 billion in 2025. BNPL continues its rapid expansion as an alternative credit and payments category embedded within financial software platforms.
- 60% of institutions are looking to increase their exposure to digital assets and tokenization. This majority interest suggests tokenized finance is moving from a niche interest to a mainstream strategic consideration.
📱 Mobile & Digital Banking Adoption
- 2.17 billion people globally used mobile banking by the end of 2025, a 35% increase since 2020. This growth rate demonstrates mobile banking’s continued expansion even as smartphone penetration in mature markets approaches saturation.
- 72% of U.S. adults reported using mobile banking apps in 2025, up from 65% in 2022 and 52% in 2019. The consistent year-over-year gains show mobile banking adoption remains on an upward trajectory rather than plateauing.
- 54% of U.S. bank customers use mobile apps as their top method for managing accounts, more than double the 26% recorded when this survey began in 2017. This shift illustrates the structural, multi-year move away from branch-first banking behavior.
- Mobile banking penetration in Europe reached 76% in 2025, with Nordic countries including Norway, Denmark, and Sweden exceeding 87%. The Nordic region continues to lead global mobile banking adoption benchmarks.
- The EU saw internet banking usage rise from 54.6% in 2019 to 67.2% in 2024. This roughly 13-percentage-point gain over five years illustrates steady, sustained digital banking migration across the EU.
- There are more than 750 digital banks worldwide serving approximately 1.8 billion customers. The scale of the digital-only and neobank segment now rivals that of many traditional banking networks.
- Leading neobanks report substantial individual scale: WeBank serves 399 million users, Nubank 100 million, and Revolut 50 million. These user bases demonstrate that digital-native banks have achieved mainstream, not niche, adoption in several major markets.
- Global neobank revenue reached $39.5 billion in 2024, an increase of 17.9% year-over-year. Neobank revenue growth continues to outpace the broader banking industry’s average growth rate.
- The global digital banking market is projected to grow from $37.49 billion in 2025 to $43.98 billion in 2026, reaching $155.44 billion by 2033 at a 19.8% CAGR. This nearly 20% compound growth rate places digital banking platforms among the fastest-growing financial software categories tracked.
📋 RegTech, Compliance & Insurtech
- The global RegTech market is projected to reach approximately $20–29 billion in 2026 (estimates vary by provider), expanding toward $105–117 billion by the early-to-mid 2030s. Despite forecasting variance, all major analyst estimates agree RegTech is compounding at roughly 19–21% annually.
- Banking is estimated to secure 46.2% of the RegTech market share in 2026, the largest of any end-user segment. Banking’s outsized share reflects its uniquely dense regulatory reporting and financial crime surveillance obligations.
- Cloud-based RegTech platforms are estimated to hold 63–75% market share in 2026 depending on the source. Cloud delivery has become the dominant deployment model for compliance software, mirroring the broader cloud shift across financial software.
- 74% of compliance respondents plan to invest in new compliance technology within the next 12 months, with adoption appetite highest among fintechs (90%). This high planned-investment rate signals continued strong near-term demand for RegTech vendors.
- The regulatory compliance management software market is valued at $13.79 billion in 2026, projected to reach $19.8 billion by 2030 at a 9.5% CAGR. This adjacent compliance software category continues expanding steadily alongside dedicated RegTech platforms.
- The global insurtech market is estimated at $23.54–35.34 billion in 2026 depending on scope definitions, with growth rates ranging from roughly 24% to 37.6% CAGR. Insurtech remains one of the highest-growth software sub-segments within the broader financial services software category.
- More than 82% of insurance companies now apply AI/ML in claims and risk evaluation. AI adoption within insurance-specific software has reached a similarly high penetration level as banking-focused AI tools.
- Automation and analytics have shortened insurance claims processing time by 50–70% while increasing fraud detection accuracy by 78%. These operational gains represent some of the most measurable efficiency benefits of insurtech adoption to date.
- Embedded insurance is maturing into an estimated $250 billion market in 2026, growing at approximately 35% annually. Embedded insurance’s growth rate outpaces most other insurtech sub-segments, reflecting the broader embedded-finance trend across financial software.
- U.S. insurance technology budgets are projected to reach $173 billion in 2026, growing 7.8% year-over-year and representing 6% of total U.S. technology spending. This budget scale illustrates that insurance technology investment now rivals many other major enterprise software categories in the U.S. economy.
- Insurance fraud is estimated to cost the U.S. industry alone approximately $308 billion annually. This figure provides important context for why fraud-detection and blockchain-based verification tools remain a top insurtech investment priority.
🖥️ Software Buying Behavior & Review Platforms
- The average B2B SaaS tool rates 4.52 stars across G2 and Capterra, with the median tool carrying 568 reviews. These benchmark figures give financial software buyers a useful reference point when evaluating vendor review credibility.
- 61% of B2B SaaS tools are currently rated between 4.3 and 4.6 stars, showing a narrow competitive clustering at the top of the market. This clustering suggests buyers should weigh review substance and recency more heavily than star rating alone when comparing platforms.
- In January 2026, G2 acquired Capterra, Software Advice, and GetApp from Gartner for approximately $110 million, consolidating the two largest B2B software discovery ecosystems into one company. This consolidation is reshaping how financial software buyers discover and compare vendors going into the rest of 2026.
- The combined G2–Gartner Digital Markets network now reaches more than 200 million annual buyers and houses nearly 6 million verified customer reviews. This scale makes the consolidated review network one of the most influential due-diligence resources for enterprise financial software procurement.
- 51% of B2B software buyers now start their research in an AI chatbot rather than a traditional search engine. This shift has direct implications for how financial software vendors should structure their content and review presence for AI-driven discovery.
- 64% of tools across categories offer a genuine free tier, providing buyers a try-before-you-buy path increasingly expected in enterprise software evaluation. Free-tier availability has become an important differentiator even in traditionally higher-touch categories like financial services software.
Conclusion
The Top 108 Financial Services Software Statistics, Data & Trends in 2026 highlight an industry experiencing rapid technological transformation, expanding market opportunities, and increasing demand for intelligent, secure, and scalable financial technology solutions. As financial institutions modernize their operations, artificial intelligence, cloud computing, digital payments, cybersecurity, and regulatory technology are becoming essential components of the global financial services software ecosystem.
With the global financial services applications market projected to reach $187.37 billion in 2026 and expand to approximately $343.64 billion by 2031, the industry’s long-term growth outlook remains strong. Increasing investments in digital transformation, financial automation, cloud-native banking infrastructure, and AI-powered analytics are creating opportunities for software providers, fintech startups, banks, insurance companies, and enterprise technology vendors.
One of the most significant financial services software trends in 2026 is the accelerating adoption of artificial intelligence. With 81% of surveyed financial services firms implementing AI at some level and 52% exploring or advancing agentic AI deployments, intelligent automation is becoming increasingly important for fraud detection, risk assessment, customer service, regulatory compliance, and financial decision-making. Financial institutions that successfully integrate AI into their existing technology infrastructure may gain advantages through improved operational efficiency, reduced processing costs, and more personalized customer experiences.
Cloud computing and core banking modernization are equally important drivers of industry growth. Approximately 68% of banks have reportedly adopted cloud-native core banking platforms, while SaaS-based financial software continues gaining market share. These developments reflect a broader transition away from inflexible legacy infrastructure toward API-enabled, interoperable, and scalable financial technology ecosystems capable of supporting real-time transactions, open banking services, and evolving customer expectations.
However, the expansion of digital financial services also introduces substantial cybersecurity, fraud prevention, and regulatory compliance challenges. With the average financial services data breach costing approximately $5.56 million in 2025, organizations must balance technological innovation with strong security controls, responsible AI governance, and comprehensive risk management strategies. Growing investments in RegTech, AI-powered cybersecurity, and automated compliance solutions demonstrate the increasing importance of operational resilience in modern financial institutions.
The continued growth of digital payments, mobile banking, open banking, and insurance technology further reinforces the industry’s transformation. Global digital payment transaction values are projected to reach $37.45 trillion in 2026, while emerging technologies such as embedded finance, real-time payments, predictive analytics, and intelligent financial automation are reshaping how financial products and services are developed, distributed, and consumed.
For financial institutions and business leaders, these financial services software statistics emphasize the importance of adopting a forward-looking technology strategy. Organizations should prioritize solutions that offer robust cybersecurity, seamless integration capabilities, regulatory compliance support, automation functionality, and measurable returns on investment. Software vendors, meanwhile, must continue innovating to meet rising expectations for transparency, reliability, personalization, and cost efficiency.
Looking beyond 2026, the future of financial services software will increasingly depend on the convergence of artificial intelligence, cloud-native infrastructure, real-time financial data, digital identity verification, and integrated financial ecosystems. Institutions capable of combining technological innovation with effective governance and customer-centric service delivery will be better positioned to navigate market uncertainty and capitalize on emerging opportunities.
Ultimately, the 108 financial services software statistics, data points, and industry trends for 2026 demonstrate that digital transformation is no longer simply a competitive advantage but a fundamental requirement for sustainable growth in the financial services sector. By understanding these market developments and making informed technology investments, financial institutions, fintech companies, and software providers can strengthen operational performance, improve customer experiences, manage emerging risks, and build more resilient businesses in an increasingly digital global economy.
If you find this article useful, why not share it with your hiring manager and C-level suite friends and also leave a nice comment below?
We, at the 9cv9 Research Team, strive to bring the latest and most meaningful data, guides, and statistics to your doorstep.
To get access to top-quality guides, click over to 9cv9 Blog.
To hire top talents using our modern AI-powered recruitment agency, find out more at 9cv9 Modern AI-Powered Recruitment Agency.
People Also Ask
What is the global financial services software market size in 2026?
The global financial services applications market is projected to reach $187.37 billion in 2026, growing at a compound annual growth rate (CAGR) of 12.92% to approximately $343.64 billion by 2031.
What are the biggest financial services software trends in 2026?
Major trends include artificial intelligence, cloud-native banking, digital payments, open banking, cybersecurity automation, RegTech, embedded finance, and AI-powered financial risk management.
How fast is the financial services software market growing?
The financial services applications market is forecast to grow at a 12.92% CAGR between 2026 and 2031, driven by digital transformation, AI adoption, cloud infrastructure modernization, and increasing regulatory requirements.
How is artificial intelligence transforming financial services software in 2026?
AI is transforming financial services through automated fraud detection, predictive analytics, credit risk assessment, customer service chatbots, anti-money laundering monitoring, and intelligent financial decision-making.
What percentage of financial services companies use AI in 2026?
Approximately 81% of surveyed financial services firms are adopting artificial intelligence at some level in 2026, with 40% reaching advanced AI maturity through scaling or transforming their operations.
What is the future of AI in banking software?
AI in banking software is expected to expand through autonomous AI agents, real-time fraud detection, personalized financial services, automated compliance monitoring, and intelligent customer support systems.
How many banks use cloud-based core banking software in 2026?
Approximately 68% of banks globally have reportedly adopted cloud-native platforms for core banking operations, reflecting growing demand for scalable infrastructure, operational efficiency, and digital banking capabilities.
What is the core banking software market size in 2026?
Core banking software market estimates vary significantly by research provider. One projection values the market at $27.6 billion in 2026, while a narrower estimate places it at approximately $10.41 billion.
Why are financial institutions adopting cloud banking software?
Financial institutions adopt cloud banking software to improve scalability, reduce infrastructure costs, accelerate product development, strengthen system integration, and support real-time banking services.
What percentage of banks are investing in cloud technology?
Survey estimates indicate that 60% of North American banks, 82% of European banks, and 83% of Asia-Pacific banks plan to increase cloud investments, highlighting widespread banking infrastructure modernization.
How much can SaaS banking software reduce operational costs?
According to the compiled industry statistics, SaaS-based core banking platforms can reduce operational costs by up to 30%, depending on implementation, infrastructure requirements, and existing technology systems.
What is the global digital payments market size in 2026?
The global digital payments market is projected to reach $37.45 trillion in transaction value in 2026, reflecting continued growth in mobile payments, online banking, digital wallets, and electronic financial transactions.
What are the latest mobile banking statistics for 2026?
Approximately 2.17 billion people worldwide used mobile banking by the end of 2025, representing a 35% increase since 2020. Mobile banking continues expanding as consumers increasingly prefer digital financial services.
What percentage of Americans use mobile banking apps?
Approximately 72% of U.S. adults reported using mobile banking applications in 2025, compared with 65% in 2022 and 52% in 2019, demonstrating sustained growth in digital banking adoption.
How many digital banks are operating worldwide?
Industry estimates indicate that more than 750 digital banks operate globally, serving approximately 1.8 billion customers through mobile-first banking platforms, digital financial products, and online banking services.
What is the digital banking market growth forecast for 2026?
The global digital banking market is projected to grow from $37.49 billion in 2025 to $43.98 billion in 2026, potentially reaching $155.44 billion by 2033 at a compound annual growth rate of 19.8%.
How is AI improving fraud detection in financial services?
AI-powered fraud detection systems can identify 30–50% more fraudulent transactions than traditional rule-based methods, according to compiled industry estimates, while helping institutions reduce false positives.
What percentage of banks use AI for fraud detection?
The compiled statistics indicate that 67% of banks use AI for fraud detection, while a broader survey reports that 90% of financial institutions use AI for fraud detection and investigation.
What is the average cost of a financial services data breach?
The average cost of a data breach in the financial services industry reached approximately $5.56 million in 2025, highlighting the importance of cybersecurity software, threat detection, and data protection.
Why is cybersecurity important for financial services software?
Cybersecurity protects sensitive financial information, prevents unauthorized transactions, reduces fraud exposure, supports regulatory compliance, and strengthens customer trust in digital banking platforms.
What is the RegTech market size in 2026?
The global regulatory technology market is projected to reach approximately $20 billion to $29 billion in 2026, depending on research methodology, with long-term annual growth estimates of around 19–21%.
How does RegTech software help financial institutions?
RegTech software automates regulatory reporting, transaction monitoring, identity verification, anti-money laundering checks, compliance assessments, and risk management processes to improve efficiency.
What percentage of financial institutions use AI for anti-money laundering?
Approximately 63% of financial institutions reportedly use artificial intelligence for anti-money laundering activities, including suspicious transaction monitoring, financial crime detection, and compliance automation.
What is the open banking market size in 2026?
The global open banking market is projected to reach $43.22 billion in 2026, with forecasts suggesting approximately 21% annual growth toward $240.31 billion by 2035.
How is open banking changing financial services software?
Open banking enables secure, permission-based financial data sharing through APIs, supporting personalized banking services, payment initiation, financial aggregation, and innovative fintech applications.
What is the global insurtech market size in 2026?
The global insurtech market is estimated at approximately $23.54 billion to $35.34 billion in 2026, depending on market definitions, with projected annual growth rates ranging from 24% to 37.6%.
How is AI transforming insurance software in 2026?
AI is improving insurance software through automated claims processing, predictive risk assessment, fraud detection, personalized underwriting, customer service automation, and data-driven policy management.
What are the benefits of financial services automation software?
Financial services automation software reduces repetitive tasks, improves processing accuracy, accelerates financial reporting, strengthens compliance monitoring, and helps institutions improve operational efficiency.
What should businesses consider when choosing financial services software?
Businesses should evaluate cybersecurity, regulatory compliance, scalability, integration capabilities, AI functionality, implementation costs, vendor reliability, customer reviews, and long-term return on investment.
What is the future outlook for financial services software beyond 2026?
Financial services software will increasingly integrate agentic AI, cloud-native infrastructure, real-time payments, embedded finance, automated compliance, and advanced cybersecurity to support more efficient and secure financial operations.
Sources
- Mordor Intelligence
- Business Research Insights
- Research and Markets
- Fortune Business Insights
- TFL Tech
- Grand View Research
- Technavio
- SDK.finance
- Market.us
- SNS Insider
- Cambridge Judge Business School
- Cambridge Centre for Alternative Finance
- Financial Innovation for Impact
- Statista
- Neurons Lab
- Wolf & Company
- Gitnux
- Finastra
- Swif
- VikingCloud
- DeepStrike
- ACAMS
- Hedge Think
- Moon Technolabs
- Fintech Global
- Bayelsawatch
- TheFinRate
- Precedence Research
- Coherent Market Insights
- Astute Analytica
- Fabrick
- SQ Magazine
- J.P. Morgan
- Future Market Insights
- Zigram
- MarketsandMarkets
- Proxymity
- GII Research
- WifiTalents
- Neontri
- Andersen
- CoinLaw
- WalletHub
- Market.biz
- Business of Apps
- American Bankers Association
- SBS Software
- Seven Insurance Brokers
- oTechWorld
- Topickz
- Reechee
- G2
- Software Advice
- GetApp
- Capterra
- Softwarefinder
- AmpliRep
- Stackmatix
- Scopic Studios
- Blastra
- VCA Software
- Citrusbug
- TechMagic
- Openkoda
- AWS Marketplace
- Next Move Strategy Consulting
- Deloitte Insights